Insurance Services in Sun City West, Connected to Your Retirement Plan

Life, long-term care, and disability coverage managed by Axberg Wealth. Home, auto, and umbrella coverage through Paul's Goosehead Insurance agency. One coordinated plan to help protect what you've built.

Is Inadequate Coverage Leaving You Vulnerable?

A single uncovered event can undo years of careful planning. A long-term care stay paid from your IRA becomes taxable income, and a large enough withdrawal can push you into a higher tax bracket and a higher Medicare premium tier two years later. A liability claim can reach the savings you set aside for retirement or for your family. The policies you carry, and the ones you don’t, are part of your financial plan whether anyone treats them that way or not.

How Axberg Wealth and Goosehead Insurance Work Together

At Axberg Wealth, insurance is never a stand-alone purchase. Life, long-term care, and disability insurance are managed directly by Axberg Wealth and coordinated with your investments, taxes, and income plan. Home, auto, and umbrella coverage are handled by Goosehead Insurance, the independent agency Paul co-owns with his nephew, Cole Moreau. Two specialized teams, one coordinated plan, with Paul keeping the whole picture in view.

A Connected Suite of Insurance Services

Every policy connects to something else in your plan. Life insurance affects what your spouse keeps and what your heirs receive. Long-term care coverage affects how much you may need to draw from tax-deferred accounts. Annuity income counts toward your tax bracket and Medicare premiums. That's why we review coverage alongside your investments and taxes, not in isolation.

Life

Life insurance can help replace income for a surviving spouse, cover final expenses, or leave a tax-efficient inheritance. We offer term, whole, and universal life, and we size coverage with your Social Security and beneficiary plan in view.

Long-Term Care

In-home care, assisted living, and nursing care are generally not covered by Medicare or standard health insurance. Long-term care coverage may help you avoid large, taxable withdrawals from retirement accounts to pay for care.

Annuities

Fixed and indexed annuities can provide a steady income stream and tax-deferred growth. Because the taxable portion of annuity income counts toward your bracket and Medicare premiums, we time it alongside Social Security and your withdrawal plan.

Meet Your Life Insurance Specialist

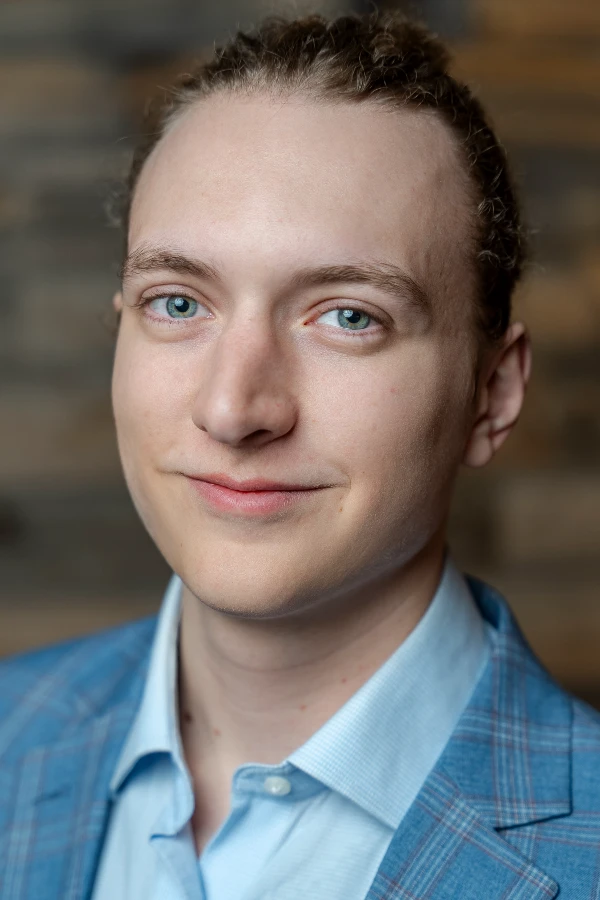
Elijah Axberg

Elijah Axberg is the Life Insurance Specialist at Axberg Wealth. He designs life insurance coverage that fits within the plan Paul builds with each client, so the policy works with your investments, tax strategy, and estate goals instead of sitting off to the side. Elijah is known for deep product knowledge and straightforward explanations. Outside the office, you’ll find him snowboarding, skating, or traveling.

Home, Auto & Umbrella Coverage Through Goosehead Insurance

Your home, your cars, and your personal liability are part of your retirement picture too. A single lawsuit or an underinsured home can reach the savings you’ve spent decades building. That’s why Axberg Wealth offers independent property and casualty coverage through Goosehead Insurance.
 
Paul is majority owner of the Sun City West Goosehead Insurance franchise. That means your home, auto, and umbrella coverage can be reviewed by people who already understand your financial plan, with liability limits set with your actual net worth in view.
 
Why Goosehead Insurance?
 
Goosehead is an independent insurance agency. Instead of selling one company’s policies, Goosehead agents compare options across a broad network of insurance carriers, including well-known national companies. Its technology lets agents quote multiple carriers quickly, so you can see your options side by side and choose the coverage, price, and service that fit you, without shopping carrier by carrier yourself.
 
 Learn more about Goosehead Insurance: www.goosehead.com
 
Meet Cole Moreau, Your Goosehead Agent

Cole Moreau, Goosehead Insurance agent in Sun City West
Cole Moreau, Paul’s nephew and a co-owner of the agency, leads its day-to-day operations. Using Goosehead’s tools, Cole can compare policies from multiple carriers in minutes and walk you through the tradeoffs between coverage, cost, and service in plain terms. When a coverage decision touches your financial plan, Cole and Paul’s team can coordinate directly, so you aren’t relaying details between them.
 
A Connected Risk Management Strategy

Goosehead handles your home, auto, and umbrella coverage. Life, long-term care, and disability insurance are managed directly by Axberg Wealth. Paul keeps both sides connected to your investments, taxes, and estate plan.

Connect with Cole
 
 Cole Moreau, Goosehead Insurance
 Email: cole.moreau@goosehead.com
 Phone: (623) 352-6656
 Agency Website: Goosehead Insurance, Paul Axberg & Cole Moreau
 
Ready to review your home, auto, or umbrella coverage? Reach out to Cole directly, or schedule a Fit Meeting with Paul to look at your coverage as part of your full plan.
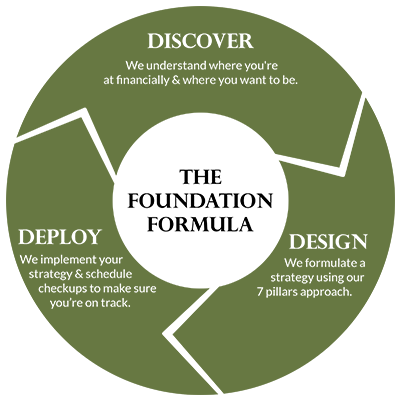
The Axberg Foundation FORMula

Insurance sits within the Risk Management pillar of the Foundation FORMula, the process Paul uses to build every client’s plan. Protecting your assets means looking at how they’re structured today and what could threaten them tomorrow: market risk, health costs, liability, and life’s unexpected events. As a CFP® professional and CPA, Paul reviews coverage through both a planning lens and a tax lens. And you work with Paul directly, not a rotating team.

DiscoverDesignDeploy

Common Insurance Questions for Retirees

What types of insurance matter most in retirement?

Most retirees should review long-term care coverage, life insurance, and liability protection through home, auto, and umbrella policies. Some also use annuities for income. If you’re still working, disability insurance protects your paycheck until retirement. Which ones matter most depends on your assets, your health, and who depends on you.

Long-term care insurance can help pay for home care, assisted living, or nursing care. Without it, those costs often come out of savings. If that savings sits in an IRA or 401(k), withdrawals are generally taxable and may raise your Medicare premiums. Medicaid can cover long-term care, but only after strict asset and income limits are met.

It depends on your situation. Life insurance can help replace income a surviving spouse loses, which matters because a survivor usually moves from joint to single tax brackets after the year of death. It can also support estate planning and cover final expenses. If your assets already meet those needs, you may not need it.

Term life insurance covers a set period and generally costs less, but it ends when the term does.
Whole life insurance lasts for life and builds cash value.
Universal life insurance offers more flexibility in premiums and death benefits.

An annuity can convert part of your savings into an income stream, and some can pay for life. Lifetime income guarantees depend on the claims-paying ability of the issuing insurance company. Some annuities also offer long-term care riders for an added cost. Annuities carry tradeoffs, including fees and surrender charges, so they’re best evaluated as one part of your income plan.

Disability insurance protects your income while you’re working and typically ends around ages 65 to 67. It doesn’t pay for extended care. Long-term care insurance is designed for that risk, and it’s generally easier and less expensive to qualify for when you’re younger and healthier.

An umbrella policy adds liability coverage above your home and auto limits. Because a large judgment can reach retirement savings, it often makes sense to consider your net worth when setting limits. Goosehead can quote umbrella coverage alongside your home and auto policies.

Options include final expense insurance, a small whole life policy, or dedicated savings. The right fit depends on your health, your budget, and what else your estate will need to cover.

Life insurance proceeds generally pass to beneficiaries free of income tax, which can give heirs cash for expenses or for taxes they may owe on an inherited IRA. Reviewing beneficiary designations and policy ownership alongside your estate plan helps your policies pay out the way you intend.

See How Your Coverage Connects to Your Plan

Please Note: The opinions expressed herein are not meant to provide specific investment advice or serve as a prediction for future stock market performance. We recommend everyone consult with a financial professional for advice related to their own, individual financial situation or plan. Goosehead Insurance and Axberg Wealth Management are separate entities. Paul Axberg is majority owner of a Goosehead Insurance franchise and may receive compensation from insurance placed through it. Goosehead Insurance and Axberg Wealth Management are not affiliated with USA Financial Securities. Annuities are best suited for long term investors. Some features may be available only by the purchase of a rider, an optional addition to an annuity or life insurance policy that is available for an additional fee. Withdrawals prior to age 59 1/2 may be subject to an additional 10% tax penalty. Surrender charges may apply. Guarantees are provided by the claims-paying ability of the underlying insurance company.

Let's Discuss Your Goals

Just fill out the form below and we’ll be in touch soon.  Don’t like forms?  We get it!  Call direct at (623) 398-0128