Insurance Services For Asset Protection, Risk Management, and Income Security.
Axberg Wealth Management is proud to partner with Goosehead Insurance to provide insurance services in Sun City West, AZ, helping protect the retirement plan you've worked to build
Is Inadequate Coverage Leaving You Vulnerable?
Without adequate insurance in key areas of life, retirees could be at risk of depleting their savings due to unexpected medical expenses, long-term care costs, or loss of income, potentially jeopardizing their financial stability and legacy.
The Axberg Wealth Management & Goosehead Insurance Approach
At Axberg Wealth Management, insurance is one piece of your overall plan, not a stand-alone purchase. Life insurance, long-term care insurance, and disability insurance are managed directly through Axberg Wealth Management, coordinated with the rest of your financial plan. Home, auto, and umbrella coverage are handled by our partner Goosehead Insurance, giving clients access to property and casualty options through an agency we trust and recommend.
A Connected Suite of Insurance Services
At Axberg Wealth Management, we recognize that insurance is one part of a coordinated financial plan. Our team in Sun City West, Arizona offers access to a range of insurance solutions — including property and casualty coverage through our partner Goosehead Insurance — designed to help protect your assets and support your goals in retirement.
Life
Long-Term Care
Supplemental
Health
Annuities
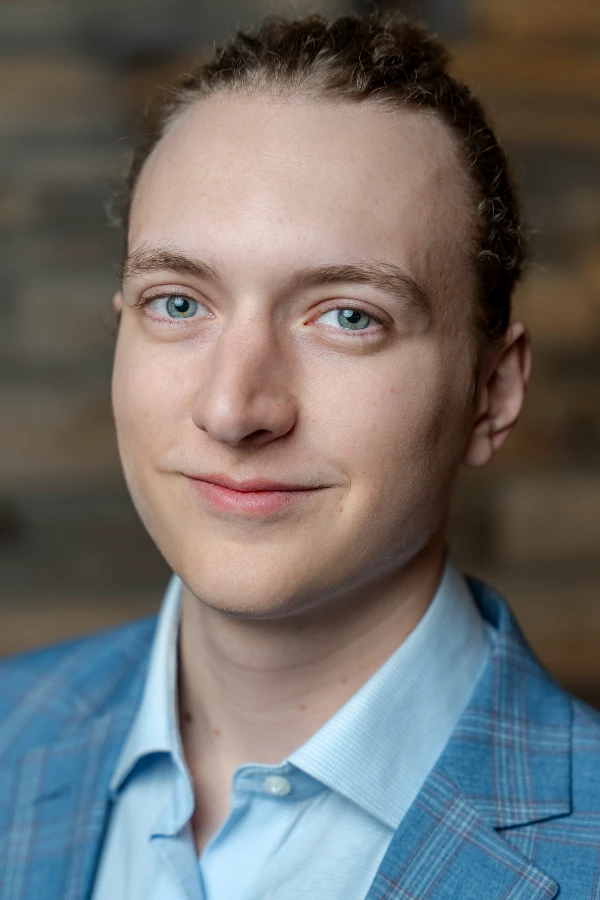
MEET YOUR LIFE INSURANCE SPECIALIST
Elijah Axberg

Expanding Our Services: Independent Property & Casualty Insurance Solutions

While property and casualty insurance is now available through Goosehead, life insurance, long-term care insurance, and disability insurance continue to be managed directly through Axberg Wealth Management. This approach ensures that every aspect of your risk management strategy is aligned with your broader financial goals.
Property and casualty insurance — home, auto, and umbrella — is available through our partnership with Goosehead Insurance, an agency we’re glad to recommend. Life insurance, long-term care insurance, and disability insurance continue to be managed directly by Axberg Wealth Management, coordinated with the rest of your financial plan. If you’d like to review your home, auto, or umbrella options, we’re happy to connect you with Cole and the Goosehead team
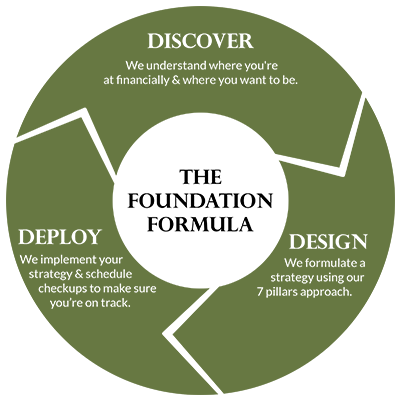
The Axberg Foundation FORMula
Insurance is part of the Risk Management pillar of the Foundation FORMula — the process Paul uses to build every client’s plan. Protecting your assets means looking at how they’re structured today and what could threaten them tomorrow: market risk, health costs, and life’s unexpected events. Insurance is one of the tools woven into that plan, alongside your investments, taxes, and estate planning.


Common Insurance Questions for Retirees
What types of insurance are essential for retirement planning?
A well-rounded retirement insurance plan should include health insurance (Medicare & Medigap), long-term care insurance, life insurance, annuities, and liability protection
(homeowners, auto, and umbrella policies). Each plays a role in preserving assets and ensuring
financial security.
How can long-term care insurance help protect my assets & independence?
Long-term care (LTC) insurance helps cover costs for home care, assisted living, and nursing home expenses. Without LTC coverage, retirees may have to spend down their assets or rely on
Medicaid, which has strict eligibility requirements.
Should I keep life insurance in retirement, or is it unnecessary?
It depends on your financial situation. Life insurance in retirement can be useful for income replacement (for a spouse), estate planning, and covering final expenses. Some retirees may no longer need it if they have sufficient assets.
What’s the difference between term life, whole life, and universal life insurance?
Term life insurance provides coverage for a set period and is generally cheaper but expires.
Whole life insurance lasts for life and includes cash value accumulation.
Universal life insurance offers more flexibility with premiums and death benefits.
How can annuities provide a reliable stream of income in retirement?
Annuities convert savings into a guaranteed lifetime income stream, helping retirees avoid
outliving their assets. Some annuities also include long-term care benefits.
What role does Medicare play in retirement, and do I need supplemental coverage?
Medicare covers hospital and medical costs, but it doesn’t cover everything. Many retirees add a Medigap or Medicare Advantage plan to reduce out-of-pocket expenses.
When should I consider transitioning from disability to long-term care insurance?
Disability insurance protects your income while working but typically expires at 65-67. Long-term care insurance becomes essential at this stage to help with extended care costs.
How can an umbrella insurance policy protect my retirement assets?
Umbrella policies provide extra liability protection beyond home and auto insurance, shielding retirees from lawsuits that could threaten their savings.
What’s the best strategy for covering final expenses without burdening my family?
Options include final expense insurance, a dedicated savings account, or a whole life insurance policy to cover funeral costs and outstanding debts.
How do I ensure my insurance policies align with my estate planning goals?
Reviewing insurance policies with estate planning in mind can help minimize taxes, ensure beneficiaries receive assets smoothly, and provide liquidity for estate-related expenses.
Take Your Insurance Services To The Next Level

Please Note: Goosehead Insurance and Axberg Wealth Management are separate entities. Goosehead Insurance and Axberg Wealth Management are not affiliated with USA Financial Securities. Annuities are best suited for long term investors. Some features may be available only by the purchase of a rider, an optional addition to an annuity or life insurance policy that is available for an additional fee. Withdrawals prior to age 59 1/2 may be subject to an additional 10% tax penalty. Surrender charges may apply. Guarantees are provided by the claims-paying ability of the underlying insurance company.